GENIUS Act Money Transmission: Checks for U.S. Businesses
By James Whitfield, Payments Specialist · Updated November 5, 2026
GENIUS Act Money Transmission: Checks for U.S. Businesses
At the provider-contract review, a U.S. business still needs a separate genius act money transmission assessment: the Act doesn't settle every licensing question. Bitcoin.com's stablecoin licensing explainer raises that distinction. Its publication date remains unverified, so it shouldn't be presented as a fresh regulatory development. A dated development is Treasury's August 17, 2026 proposed rule addressing payment stablecoin issuance, offering, and sale.
That proposal isn't a final rule. Businesses seeking the separate spending context can use the crypto spending and Apple Pay guide; this review concerns payment operations, custody, and responsibility.
Where genius act money transmission analysis starts
The Act's text includes preemption of state charter, licensing, or other authorization requirements for specified federally qualified payment stablecoin issuers and approved subsidiaries of insured depository institutions or credit unions. That is narrower than an exemption for every business accepting or handling stablecoins.
An entrepreneur shouldn't extend issuer-specific treatment to a marketplace, payment intermediary, or merchant without qualified counsel examining the actual activity.
Treasury's August proposal concerns implementation of section 3. Treasury also proposed rules addressing the Act's anti-money-laundering and sanctions compliance program requirements. These developments warrant monitoring, but neither a proposal nor commentary establishes a business-specific licensing conclusion.
Separate the three compliance decisions
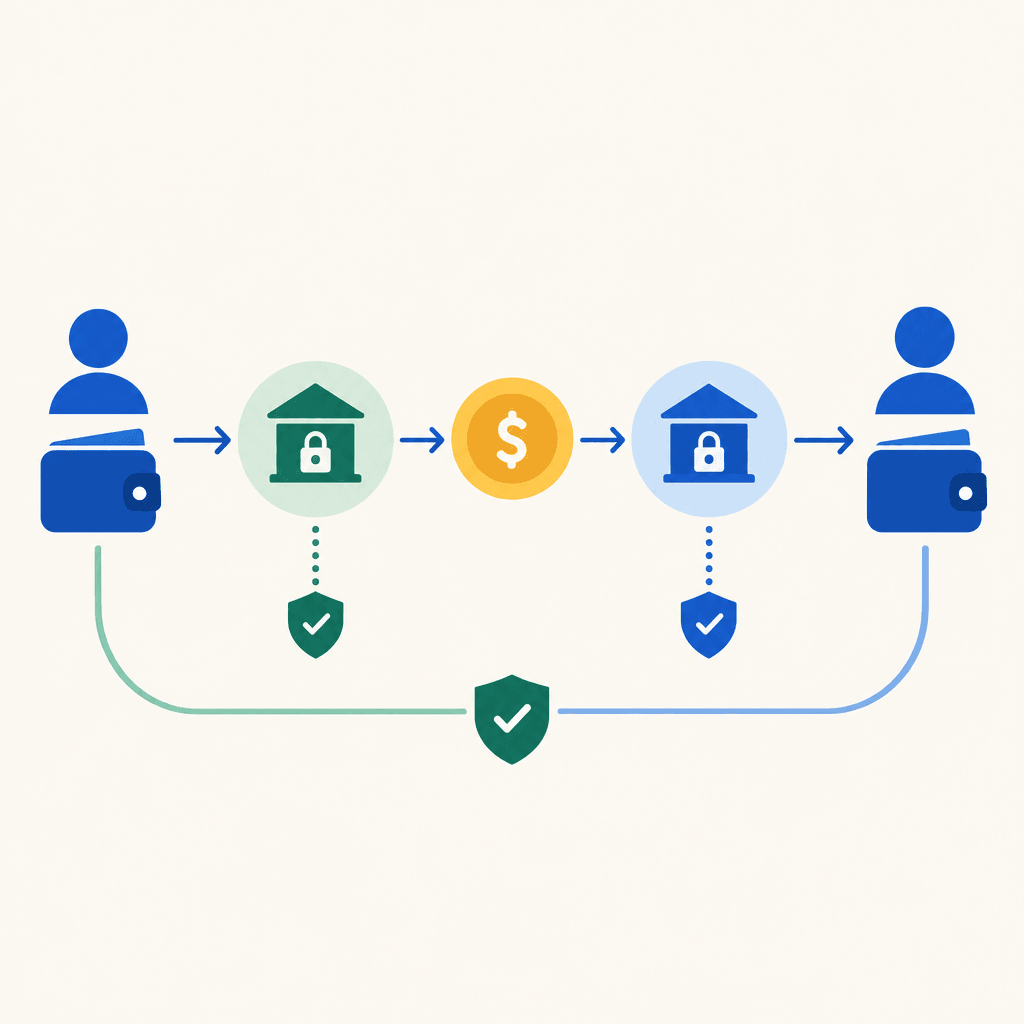
A useful genius act money transmission review produces separate conclusions rather than a single “compliant” label.
- Stablecoin legislation: Which entity issues the stablecoin, and which issuer-specific provisions apply?
- State money transmission requirements: Does the business's activity fall within each relevant state's definitions, exclusions, or exemptions?
- Federal MSB registration: Does the operating model trigger federal money services business registration or qualify for an applicable exemption?
K&L Gates reports that 49 states and the District of Columbia have licensing laws covering payment-services businesses. Covered activities generally include issuing or selling payment instruments or stored value and receiving money or monetary value for transmission.
State definitions differ. Some address virtual currency through money-transmission laws; others maintain separate digital-asset regimes. Cryptonews.net's analysis also cautions that a merchant agreement alone doesn't establish the federal exemption under discussion. Public-blockchain settlement needs particular attention under its clearance-and-settlement condition.
A provider's license is a due-diligence document, not an automatic answer about its customer's obligations.
Build the genius act money transmission checklist around control
The operating model matters more than the checkout label. Accepting payment for a business's own services and collecting payments owed to independent sellers are different scenarios for assessment, not predetermined licensing outcomes.
- Who controls funds or keys? Identify who can sign transactions, authorize withdrawals, freeze balances, or redirect payments, including through administrative access.
- Whose payments are processed? Distinguish business revenue from funds collected for sellers, contractors, or other customers.
- Where do funds move? Record customer, counterparty, and business locations alongside wallets, networks, intermediaries, and destinations.
- Who settles and refunds? Document settlement instructions, pending balances, underpayments, failed transfers, and refund authority.
- What does the contract allocate? Compare written duties with actual permissions, including subcontractors and exception handling.
Stablecoin custody responsibilities include operational access, not just the name on a wallet. Businesses operating merchant wallets can use the merchant hot-wallet security checks to organize a separate technical review; security controls don't establish licensing status.
Require evidence from the payment provider
For genius act money transmission due diligence, the provider should identify the contracting entity, applicable authorizations, supported business activities, geographic restrictions, and any reliance on partners. Counsel should verify whether that evidence covers the proposed flow.
The written responsibility allocation should address customer screening, AML and sanctions controls, recordkeeping, transaction monitoring, incident escalation, and refunds. Ambiguous clauses need clarification before launch. The business access verification checklist provides a related framework for separating infrastructure announcements from contractual access.
For example, WaldenPay's payment links let a creator request a fixed USD amount payable in supported crypto without requiring the payer to hold an account. That feature doesn't determine the creator's licensing position. WaldenPay is operated by BlueHouse Software B.V. through a licensed partner model; use remains subject to AML and regulatory requirements.
FAQ
Does genius act money transmission preemption cover every merchant?
The cited preemption concerns specified issuers and subsidiaries. A merchant's activity requires its own assessment.
Does federal registration replace state licensing?
Federal registration and state licensing are separate questions. Counsel should document the basis for each conclusion.
Does accepting payment for a business's own services require licensing?
The scenario needs review against applicable definitions and exemptions. It shouldn't be treated as identical to processing payments for others.
Does outsourcing settlement remove the business's obligations?
Outsourcing doesn't establish an exemption. Actual control, contractual duties, customer relationships, and settlement arrangements still matter.
Put the payment flow in counsel's hands
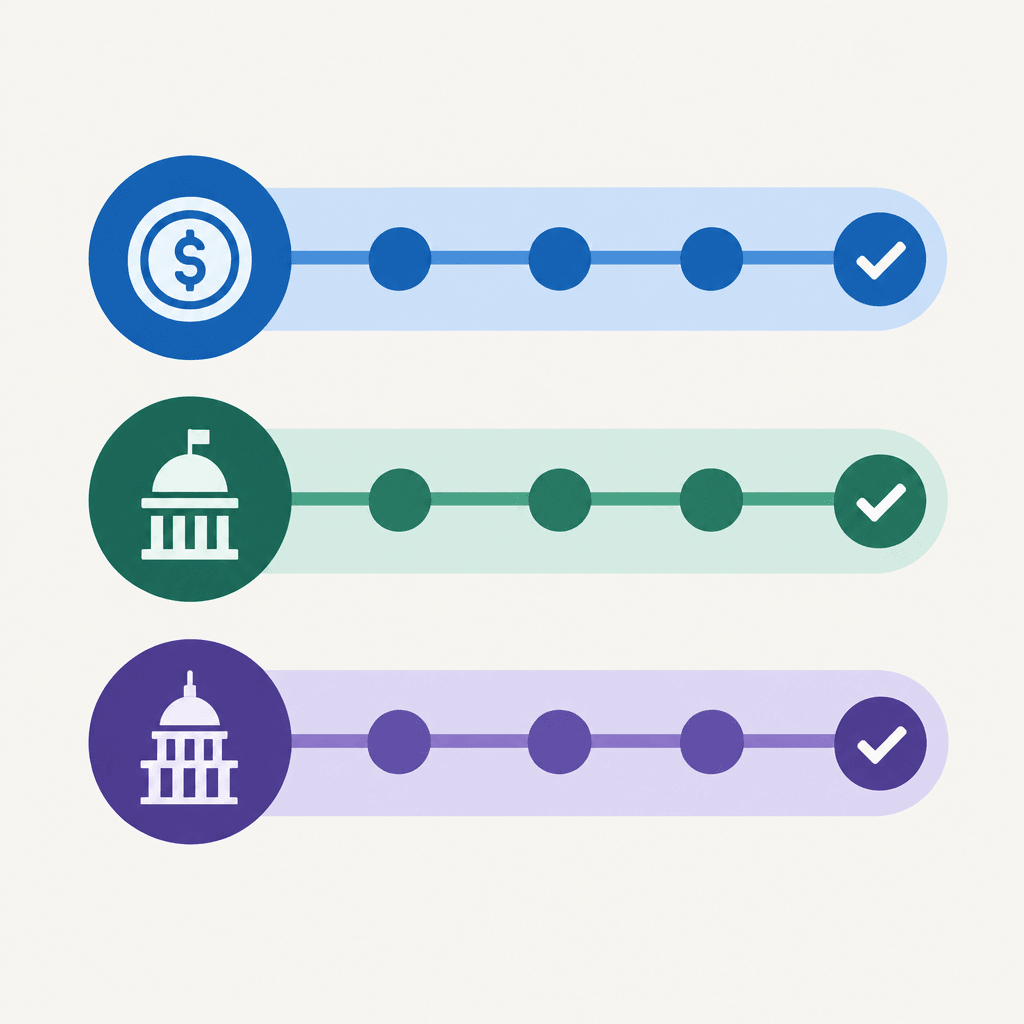
The review packet should contain a custody diagram, provider agreements, customer and counterparty locations, and a written responsibility allocation. Each arrow needs an owner:
Payer wallet - receiving address and key controller - pending balance - settlement destination - refund route and authorizer.
Qualified counsel should assess each entity's role, jurisdictional exposure, claimed exemptions, and applicable implementation timing. This checklist isn't legal advice.
Prepare the provider review
Before enabling WaldenPay payment collection, the business should send its payment-flow diagram and proposed agreement to qualified counsel for a genius act money transmission assessment.
Get started with WaldenPayRelated
- Open USD Business Cards: What Businesses Must Verify
- Apple Cash Identity Verification: Checks for Reload Users
- BTCPay Server Security Update: Merchant Hot-Wallet Checks
- Revolve Card Breach: What Shoppers Should Check Now
- ChatGPT Plus Declined: VPN Triggered Fraud Check (2026)
- Pay for Amazon Web Services with Crypto