Best Crypto Card 2026: How to Choose the Right One
By Elena Petrova, Blockchain Researcher · Updated September 24, 2026
A useful shortlist starts with disqualifiers. An unavailable regional program, unsupported deposit network, or unsuitable prepaid-payment policy outweighs an attractive rewards headline. Applications and individual purchases aren't guaranteed, even when the merchant accepts the card's network.
For rewards seekers, the meaningful comparison is rewards actually earned after exclusions and costs. For crypto-funded spending, it's the path from an existing wallet balance to a completed purchase. Wallet-linked products add another question: which permissions allow the service to spend assets?
WaldenPay publishes this guide and appears as a prepaid-card example, not an independently selected overall winner. That commercial interest matters. This decision framework complements the site's card-by-card comparison, distinguishes published terms from testing and unknowns, and provides an eligibility checklist, worked cost examples, and a final selection process.
The explanation of how crypto cards work covers the underlying mechanics. Each comparison still needs the terms for the applicant's specific regional program.
Crypto Debit, Credit, and Prepaid Cards Solve Different Problems
Spending cryptocurrency and earning cryptocurrency are different jobs. A conventional credit card can award crypto while purchases create an ordinary bill payable under its credit agreement. A crypto-funded card instead accesses assets or a balance already supplied by the holder. Debit-style cards draw on an available account balance, but their terms determine whether crypto is sold before spending or during payment processing. The explanation of what a crypto card is separates the reward asset from the money actually funding purchases.
Prepaid cards require funding before spending. WaldenPay is a virtual prepaid card, not a bank account or credit product; cryptocurrency converts to card balance when loaded. The holder spends that funded balance rather than borrowing against future income. The crypto prepaid card guide explains prefunding and balance management. By contrast, unsecured credit creates repayment obligations and may charge interest. Collateral-backed borrowing uses pledged assets to support debt, introducing borrowing costs, collateral requirements, and potential liquidation if asset values fall. Neither borrowing model should be evaluated as a prepaid balance.
Virtual describes the format, not the funding model. Digital credentials typically include a card number, expiration date, and security code; they can represent prepaid, debit, or credit products. The explanation of what a virtual card is distinguishes those credentials from the underlying account. Physical cards offer different checkout options, but neither format alone establishes ATM access, credit availability, or payment protections.
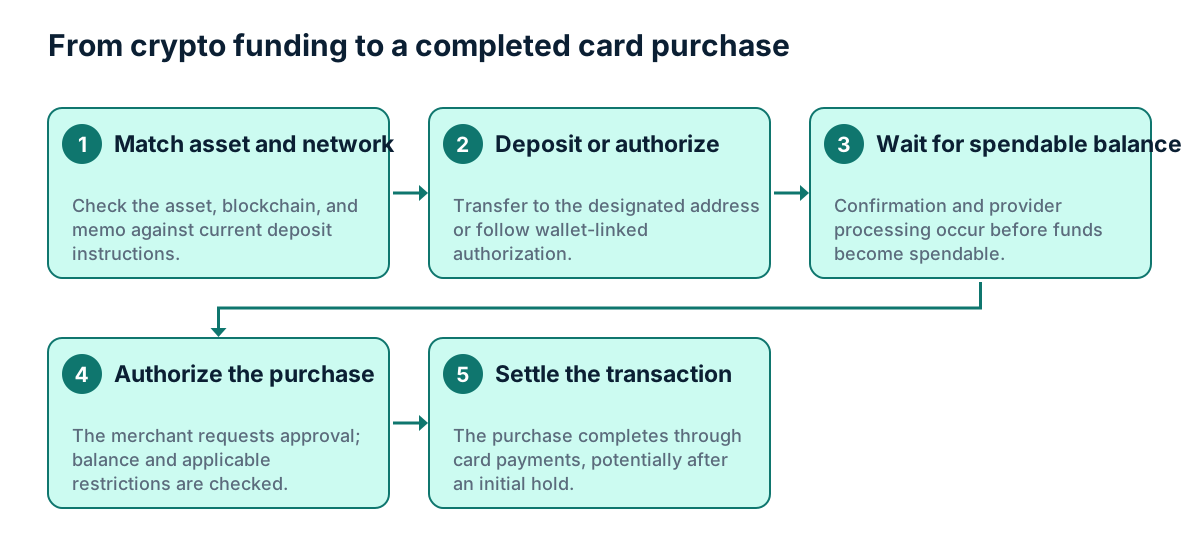
How Crypto Moves From a Wallet to a Card Purchase
A blockchain deposit and a card purchase are separate transactions. Card-network acceptance doesn't mean the merchant receives cryptocurrency. The explanation of how crypto cards work traces the bridge between the funding asset and merchant payment.
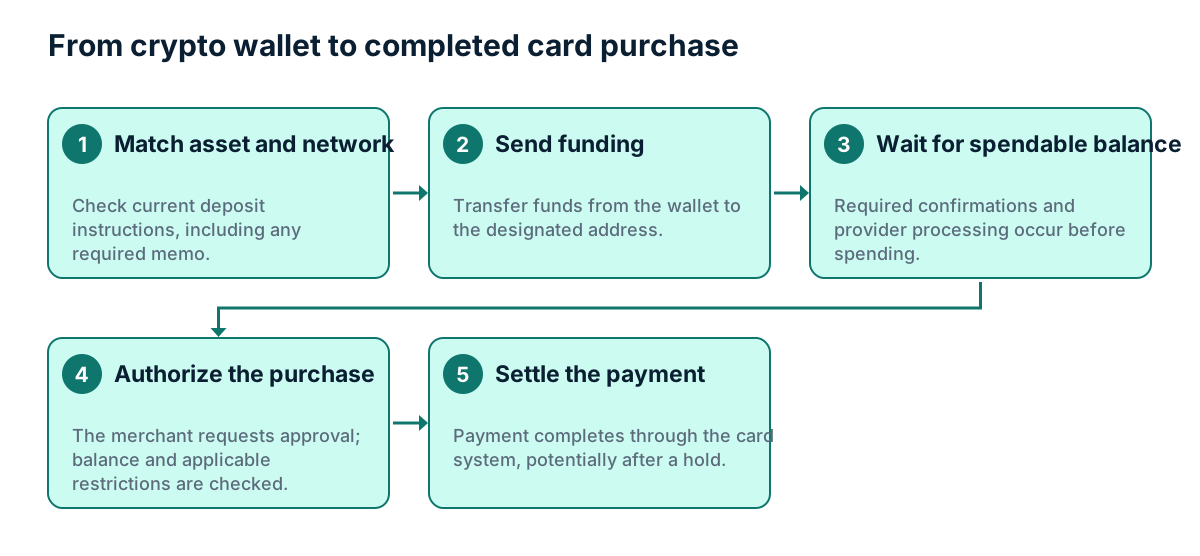
- Asset and network selection: The sender matches the asset, blockchain, and any required memo to current deposit instructions.
- Funding: Funds move to the designated address. Wallet-linked models may instead rely on an authorization process.
- Balance availability: Required confirmations and provider processing occur before deposited funds become spendable.
- Authorization: The merchant requests approval; the available balance and applicable restrictions are checked.
- Settlement: The payment completes through the card system, potentially after an initial hold.
WaldenPay's crypto virtual card converts cryptocurrency to card balance at loading time and is issued instantly after funding. Its account wallet provides unique deposit addresses per supported network. Email-only signup requires no identity documents for standard use, but use remains subject to AML and regulatory requirements.
Conversion at purchase works differently: assets remain exposed to their price movements until the relevant conversion event. Some models use wallet permissions to source payment. A wallet-linked label alone doesn't establish custody, the scope of spending authority, or when assets leave the holder's control.
The explanation of how virtual cards work separates credentials from authorization and settlement. An approved authorization isn't necessarily a finalized charge.
And direct Bitcoin payments follow another route: the recipient accepts an on-chain payment rather than a card-network transaction.
Product-flow video: WaldenPay: The No KYC Crypto Card for Everyday Spending illustrates the product workflow. Its title isn't a promise of anonymity, unrestricted eligibility, or guaranteed approval; document-free standard signup doesn't remove compliance obligations.
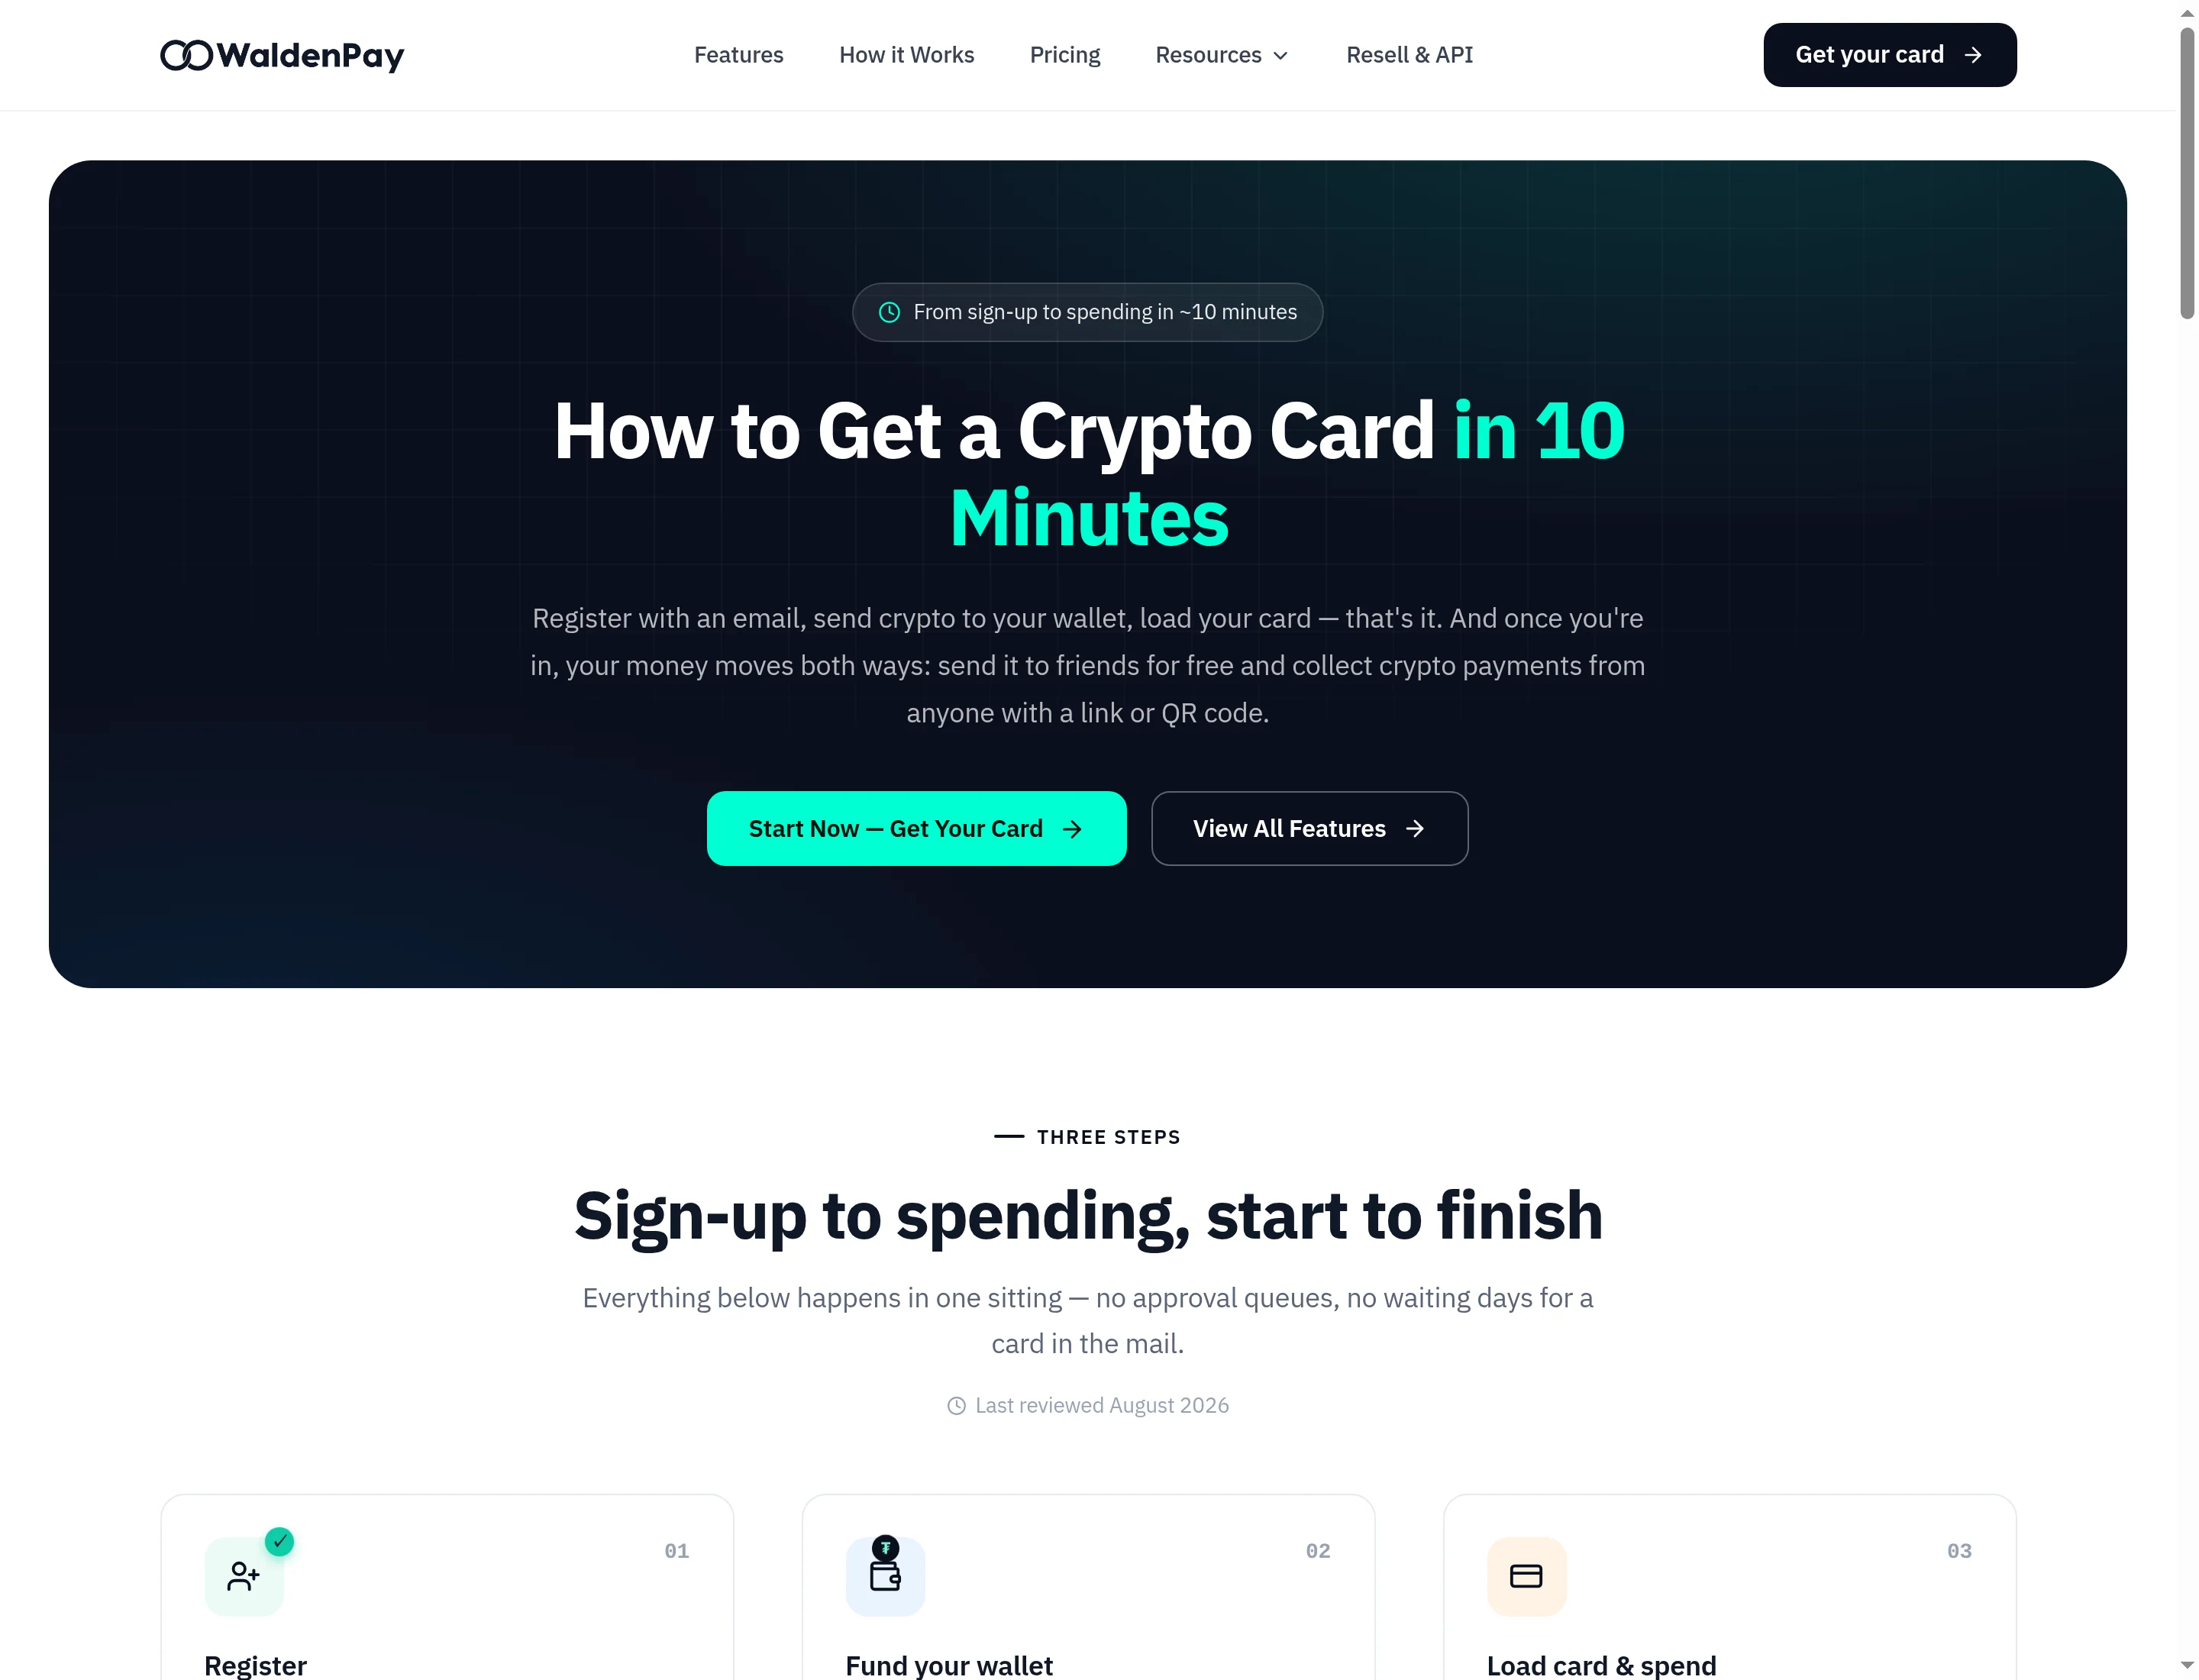
Explore Prefunded Crypto Spending
WaldenPay converts supported crypto into card balance at loading time, so purchases use a prepaid balance rather than spending directly from a blockchain wallet. It's privacy-focused, not anonymous, and use remains subject to AML and regulatory requirements.
The Best Crypto Card Depends on the Spending Job
Convenient spending access, fewer funding steps, and useful transaction records can matter more than headline rewards. The overview of crypto card benefits explains those practical advantages, but selection still starts with the holder's actual payment pattern.
The best crypto card for a rewards seeker may be unsuitable for a freelancer spending stablecoins. Without verified regional product evidence, the responsible early shortlist identifies funding models and disqualifiers rather than named winners. The table below describes categories to investigate, not confirmed availability.
| Spending job | Suitable model | Must-have feature | Disqualifying drawback | Next verification step |
|---|---|---|---|---|
| US rewards seeker | Eligible conventional credit with crypto rewards | Useful rewards on actual purchases | Interest or mandatory costs outweigh rewards | Check state eligibility, reward currency, exclusions, caps, and repayment terms |
| UK, EEA, or other regional spender | Locally eligible debit-style or prepaid program | Required recurring payments and checkout options | Wrong regional product or unsupported payment type | Confirm exact residence, application status, and regional terms |
| Existing stablecoin holder | Funded card supporting the existing asset-network pair | Direct supported funding route | Unsupported network or excessive intermediate transfers | Match deposit instructions, funding minimum, and loading costs |
| Freelancer | Crypto collection plus funded-card spending | Identifiable receipts and usable payment records | Collection records don't support reconciliation | Trace an invoice from client payment to spendable balance |
| Traveler or digital nomad | Eligible card with remote management | Destination checkout access and manageable holds | No confirmed cash access when cash is essential | Check residence rules, mobile wallets, hold policies, and ATM terms |
| Privacy-conscious consumer | Program with documented data practices | Clear collection, retention, and verification policies | Unsubstantiated anonymity promises | Read privacy terms and conditions for additional verification |
| Self-custody-oriented holder | Wallet-linked spending with bounded permissions | Understandable spending authority and revocation | Permissions exceed intended exposure | Inspect supported wallets, intermediaries, and revocation steps |
| Business purchaser or advertiser | Funded card permitted by merchant policies | Reliable billing workflow and transaction records | Required merchant rejects the card category | Confirm prepaid eligibility, recurring billing, and balance requirements |
Freelancers need a collection workflow too
Network compatibility matters before spending begins. A practical process for accepting crypto payments connects client instructions, payment confirmation, and bookkeeping rather than leaving each invoice as an unexplained wallet deposit.
WaldenPay's Collect Payments creates fixed USD requests from $1 to $10,000 with a description, shared through a link or QR code. The payer needs no WaldenPay account and can pay in 135+ supported cryptocurrencies across 35+ networks. The payer covers a 0.2% conversion fee; the creator receives the exact requested USD amount in the account wallet. That receipt isn't itself a completed card load.
A useful operational check follows the same invoice reference through the payment request, receipt, wallet balance, and later card funding. Collection convenience doesn't establish that the resulting records meet every business's accounting needs.
Travel and business spending need operational checks
WaldenPay supports Apple Pay and Google Pay. Its Telegram bot handles card orders, recharges, balance checks, and transaction alerts. These features support remote management; they don't establish residency eligibility or guarantee acceptance for lodging or advertising purchases.
For business spending, a stable funded balance and clear records may matter more than rewards. But WaldenPay remains prepaid. It doesn't bypass merchant rules, fraud checks, or recurring-payment restrictions. Where a required merchant excludes prepaid cards, another permitted payment method is necessary.
Privacy-sensitive holders should examine what information is collected and why. Minimal signup requirements don't make card spending untraceable or remove AML obligations.
When a conventional payment card is simpler
A holder paid in dollars who wants ordinary purchases and predictable billing may gain little from adding crypto acquisition and funding steps. A conventional payment card can be simpler when crypto isn't already part of the cash flow, or when required borrowing, cash access, or merchant policies don't match a prepaid product.
Country Eligibility Comes Before Overseas Merchant Acceptance
Residence determines whether an applicant can obtain and maintain a particular card. Overseas acceptance concerns purchases after issuance. A program can support cross-border spending without accepting applicants from every country where its card network operates.
Citizenship, residence, travel destination, and merchant location aren't interchangeable. Citizenship may be relevant under application terms, but it doesn't substitute for a qualifying residential address. A vacation doesn't necessarily change residence, while relocation may require account updates or affect continued eligibility. Merchant location describes the purchase, not the applicant's right to open an account.
Regional versions matter just as much as the brand name.
Different programs under one brand may have different issuing entities, funding arrangements, rewards, and verification requirements. Any comparison row must identify the version available to the applicant. An attractive offer from another region isn't evidence that the same terms apply locally.
An eligibility worksheet that preserves the evidence
| Field | Evidence to record | Reason to pause |
|---|---|---|
| Residence | Exact supported country and residential-address requirements | Only worldwide acceptance is advertised |
| State or territory | Explicit inclusion or exclusions for the applicant's location | National marketing leaves local eligibility unclear |
| Issuing entity | Legal issuer in the applicable cardholder agreement, separate from the platform operator | The agreement belongs to another regional program |
| Application status | Open applications, invitation, waitlist, or existing-holder service | A product page doesn't confirm new applications |
| Product variant | Prepaid, debit, or credit; virtual and physical availability | The advertised feature belongs to another variant |
| Verification | Signup information, required checks, and circumstances requiring additional information | Marketing claims conflict with application terms |
| Evidence date | Date reviewed, official page, agreement version, and unresolved questions | No dated evidence supports the conclusion |
A worksheet should label each material point confirmed, unavailable, or unresolved. An unanswered eligibility question stays unresolved rather than becoming an assumed approval. Saved terms and written support clarification help preserve what was checked, but neither guarantees an application outcome.
Regional checks must remain separate
- United States: Evidence should identify the US program and any state or territory exceptions. A worldwide-acceptance statement doesn't establish US eligibility, and a rewards credit application needs its own approval and repayment checks.
- United Kingdom: UK residency requires explicit confirmation. EEA availability isn't a substitute, even when the same brand markets both programs.
- EEA: The exact country should appear in supported-market documentation. "Europe" is too imprecise to establish an applicant's eligibility.
- Other markets: Current residence, address requirements, and additional applicant conditions need confirmation. Availability in a neighboring country doesn't establish access.
- Travel and relocation: Temporary purchases abroad and a permanent address change may carry different requirements. Account-maintenance terms deserve review before relocation.
Issuance, delivery, and checkout access are different checks
Virtual issuance doesn't establish physical-card delivery. Physical delivery doesn't establish mobile-wallet provisioning. Each requires separate confirmation for the regional product and intended setup. Likewise, mobile-wallet compatibility doesn't establish ATM access, offline-terminal support, or acceptance of prepaid cards for a particular purchase.
US residents should confirm their eligibility with WaldenPay before signing up. Its stated reach of 150M+ merchants worldwide describes card-network reach, not an applicant-country list or guaranteed authorization. WaldenPay is operated by BlueHouse Software B.V. in Rotterdam, Netherlands, through a licensed partner model; the operator's location alone doesn't establish the applicant's eligibility.
So the best crypto card shortlist needs two separate checks: permission to obtain and maintain the account, and suitability for intended purchases. Available balance, merchant holds, prepaid restrictions, and authorization controls still matter after issuance.
The analysis of crypto adoption by country adds market and regulatory context. High adoption doesn't prove that a particular card is available, permitted, or suitable for an individual resident.
How the Best Crypto Cards Are Evaluated
A defensible best crypto card verdict begins with eligibility and open applications. Only then do fees, rewards, and convenience become useful comparisons. An unavailable product belongs outside an actionable shortlist, regardless of its advertised benefits.
Eligibility and application status are gates
Each candidate needs an identifiable regional version, eligible residency, relevant state restrictions, and application status. Open applications, waitlists, and discontinued programs aren't equivalent. Unknown eligibility remains unknown; overseas merchant acceptance cannot fill that gap.
Required funding routes and essential payment capabilities are also pass/fail gates. If a holder needs a particular asset-network pair, recurring payments, or cash withdrawals, that capability needs documented support. A failed requirement excludes the candidate for that spending job. An unresolved requirement makes the recommendation conditional, not ready to fund.
The same criteria apply to every candidate
The evidence scorecard is unweighted. It organizes findings without implying that a numerical ranking or comparative performance test has been completed.
- Documented costs: Record published issuance, recurring, funding, inactivity, withdrawal, and financing charges where applicable. Missing information isn't zero.
- Funding compatibility: Check asset-network pairs, minimum deposits, required memos, and steps before funds become spendable.
- Custody and security: Identify asset control, wallet permissions, account recovery, authentication, and available card controls.
- Limits and access: Check purchase limits, load limits, ATM access, recurring-payment suitability, and mobile wallet support separately.
- Rewards: Record base earning, exclusions, caps, payout delays, redemption conditions, subscriptions, and required token holdings.
- Operations and support: Examine deposit processing, refunds, dispute routes, support access, and transaction alerts.
- Exit options: Establish how remaining balances can be recovered, whether closure requires additional checks, and which documented restrictions apply.
Identity language needs equal care. Know Your Customer rules concern customer identification and related checks. Document-free signup doesn't establish an absence of monitoring or future verification obligations. The no-document crypto card comparison provides card-by-card discussion of onboarding claims and practical limitations, rather than treating privacy as anonymity.
Evidence needs a traceable record
Each material claim needs an evidence-ledger entry: provider, regional version, assessed field, official source URL, actual verification date, and evidence type. Desk research means reviewing documentation. A hands-on test additionally needs recorded conditions and an observed result. Reading a funding-speed claim isn't testing funding speed.
Specific third-party findings should carry an "as of July 2026" label alongside the actual recorded verification date. Neither label substitutes for evidence. Without issuer documentation or a recorded test, the field stays unverified; search-result dates and comparison headlines don't establish availability.
A material-change log should preserve what changed, when it was checked, and which verdict it affected.
Verdicts should reflect evidence quality
Useful labels include "fits the documented requirements," "conditional fit," and "insufficient evidence." Numerical scoring would require verified inputs and disclosed weights.
WaldenPay publishes this guide and has a commercial interest in card signups. That relationship isn't proof of superiority: the same evidence standard applies to its claims, limitations, and unknowns. Any actual referral relationships require separate disclosure beside relevant recommendations; none should be inferred.
A strong comparison shows why a card fits a particular holder, what disqualifies it, and which important facts remain unknown.
Check the Exact Coin and Network, Not Just the Asset Count
An asset ticker doesn't identify a deposit route. The deposit screen must match the exact asset and network, then supply the address, any memo or tag, minimum deposit, and confirmation requirements. The altcoin debit card guide puts compatibility ahead of headline coin counts.
Polygon USDT, Arbitrum, Tron, Solana, Base, and TON each require route-specific checks; BEP20 generally identifies the token standard associated with BNB Smart Chain. XRP, Litecoin, Dogecoin, and Monero requests also need explicit support confirmation, not inference from similar assets. The XRP debit card guide adds asset-specific context, while live instructions govern destination-tag requirements.
WaldenPay supports 135+ cryptocurrencies across 35+ networks, including USDT, USDC, BTC, ETH, SOL, TRX, and LTC. Its account wallet provides unique deposit addresses per supported network, but aggregate coverage isn't an exhaustive deposit matrix. The USDT virtual card guide connects verified funding routes to card use.
A USDC virtual card or USDT-funded product can reduce exposure to volatile-asset price movements before loading, but stablecoins can deviate from their intended value. Volatile assets add price uncertainty while awaiting funding. Stablecoins explained covers why a price target doesn't make tokens on different chains interchangeable.
A wallet deposit and a spendable card balance aren't necessarily the same thing. Some funding flows require another step; WaldenPay converts loaded cryptocurrency into card balance at loading time. The explanation of USDT payments distinguishes sending tokens from completing a card purchase.
Wallet compatibility means the sending wallet or exchange can use the exact destination route and required instructions. A multi-chain card doesn't make unsupported transfers recoverable. The network fee explanation distinguishes on-chain costs from internal ledger transfers; sufficient transaction-fee assets may be needed before sending.
Read Beyond Headline Fees Before Comparing Costs
The best crypto card depends on the cost of the full spending cycle, not just the advertised loading fee. An unsupported cost belongs in a comparison as "unknown," not $0. The Crypto Card Fee Index provides a repeatable research framework, not an established numerical ranking without accessible supporting evidence.
Issuance pays for card creation; annual or subscription charges pay for continued access or benefits. Loading fees apply when funding, while asset-conversion costs may arise when crypto becomes spendable money. Inactivity charges depend on specified conditions. Financing costs concern borrowed balances rather than prepaid spending. The crypto card fee breakdown explains these separate categories.
General-market pricing: Foreign transaction charges and conversion spreads require separate checks. A provider can advertise no top-up fee while using a conversion rate less favorable than a contemporaneous reference rate; that doesn't establish that every provider does so. The foreign transaction fee guide explains the distinctions without treating missing disclosures as free service.
Every percentage needs a fee base: the amount sent, amount credited, purchase amount, or cash withdrawn. A minimum charge can override percentage arithmetic on small transactions. Conditional waivers require their own evidence, including qualifying activity, subscription requirements, allowance periods, and what happens after an allowance runs out.
And ATM charges can include separate program and machine-operator costs. Blockchain network fees pay for on-chain activity, not card issuance. Minimum loads aren't fees, but a hypothetical $25 minimum prevents a $10 funding test. Comparison pages can organize these differences; current program terms should control the calculation, with unresolved components left visible.
Model Domestic Spending, Travel, and Cash Access Before Committing
Three hypothetical baskets make cost research concrete: $1,000 in domestic purchases, $1,000 in foreign-currency purchases, and a $200 ATM withdrawal. These are budgeting inputs, not provider prices, product limits, or claims of availability. A holder should apply the same assumptions to each eligible candidate rather than compare one product's promotional month with another's normal pricing.
Define the baskets before entering prices
| Planning basket | Required inputs | Decision rule |
|---|---|---|
| $1,000 domestic purchases | Required funding amount, funding fee base, applicable recurring charges, qualifying rewards | Compare the documented cost of making $1,000 spendable, not merely sending $1,000. |
| $1,000 foreign-currency purchases | Documented settlement method, applicable foreign transaction charges, conversion costs, recurring charges | Leave the total "not established" if a material pricing component is missing. |
| $200 ATM withdrawal | Documented ATM capability, withdrawal limits, program charge, operator surcharge, applicable funding costs | Exclude unsupported cash access rather than assign a zero cost. |
For each basket, the research record should identify the regional product, tier, source, verification date, and whether the account is new or existing. One-time issuance belongs in a new-account comparison; it shouldn't be charged again in every later month. Conditional rewards should remain separate until their eligibility, caps, and payout conditions are established.
Provider-neutral travel worksheet
The travel basket represents $1,000 of planned foreign-currency purchases expressed as a USD budgeting amount. It doesn't establish the final posted amount. The worksheet needs the program's documented treatment, transaction currencies, and relevant settlement assumptions before producing a total.
Travel cost formula: documented funding costs + applicable recurring costs + documented foreign transaction charges + documented conversion costs - realizable rewards.
Only separately charged components belong in the sum. If a documented conversion cost is already embedded in the posted purchase amount, adding it again would double-count it. A stated waiver needs its conditions checked. Missing pricing stays "not established," rather than being replaced with an assumed industry rate.
Provider-neutral cash-access worksheet
Cash-access cost formula: documented cost of funding the withdrawal + program withdrawal charge + ATM operator surcharge + other documented applicable charges.
The $200 cash principal is separate from those costs. The required available balance must cover both. A percentage withdrawal fee and its minimum must be applied according to the terms, not automatically added together.
Card-network branding doesn't establish ATM support. Neither does mobile wallet compatibility prove that a particular ATM can use the credential. If withdrawal capability is undocumented, the result is "not established"; if expressly unsupported, the candidate fails the cash-access requirement.
Separate domestic loading example: WaldenPay
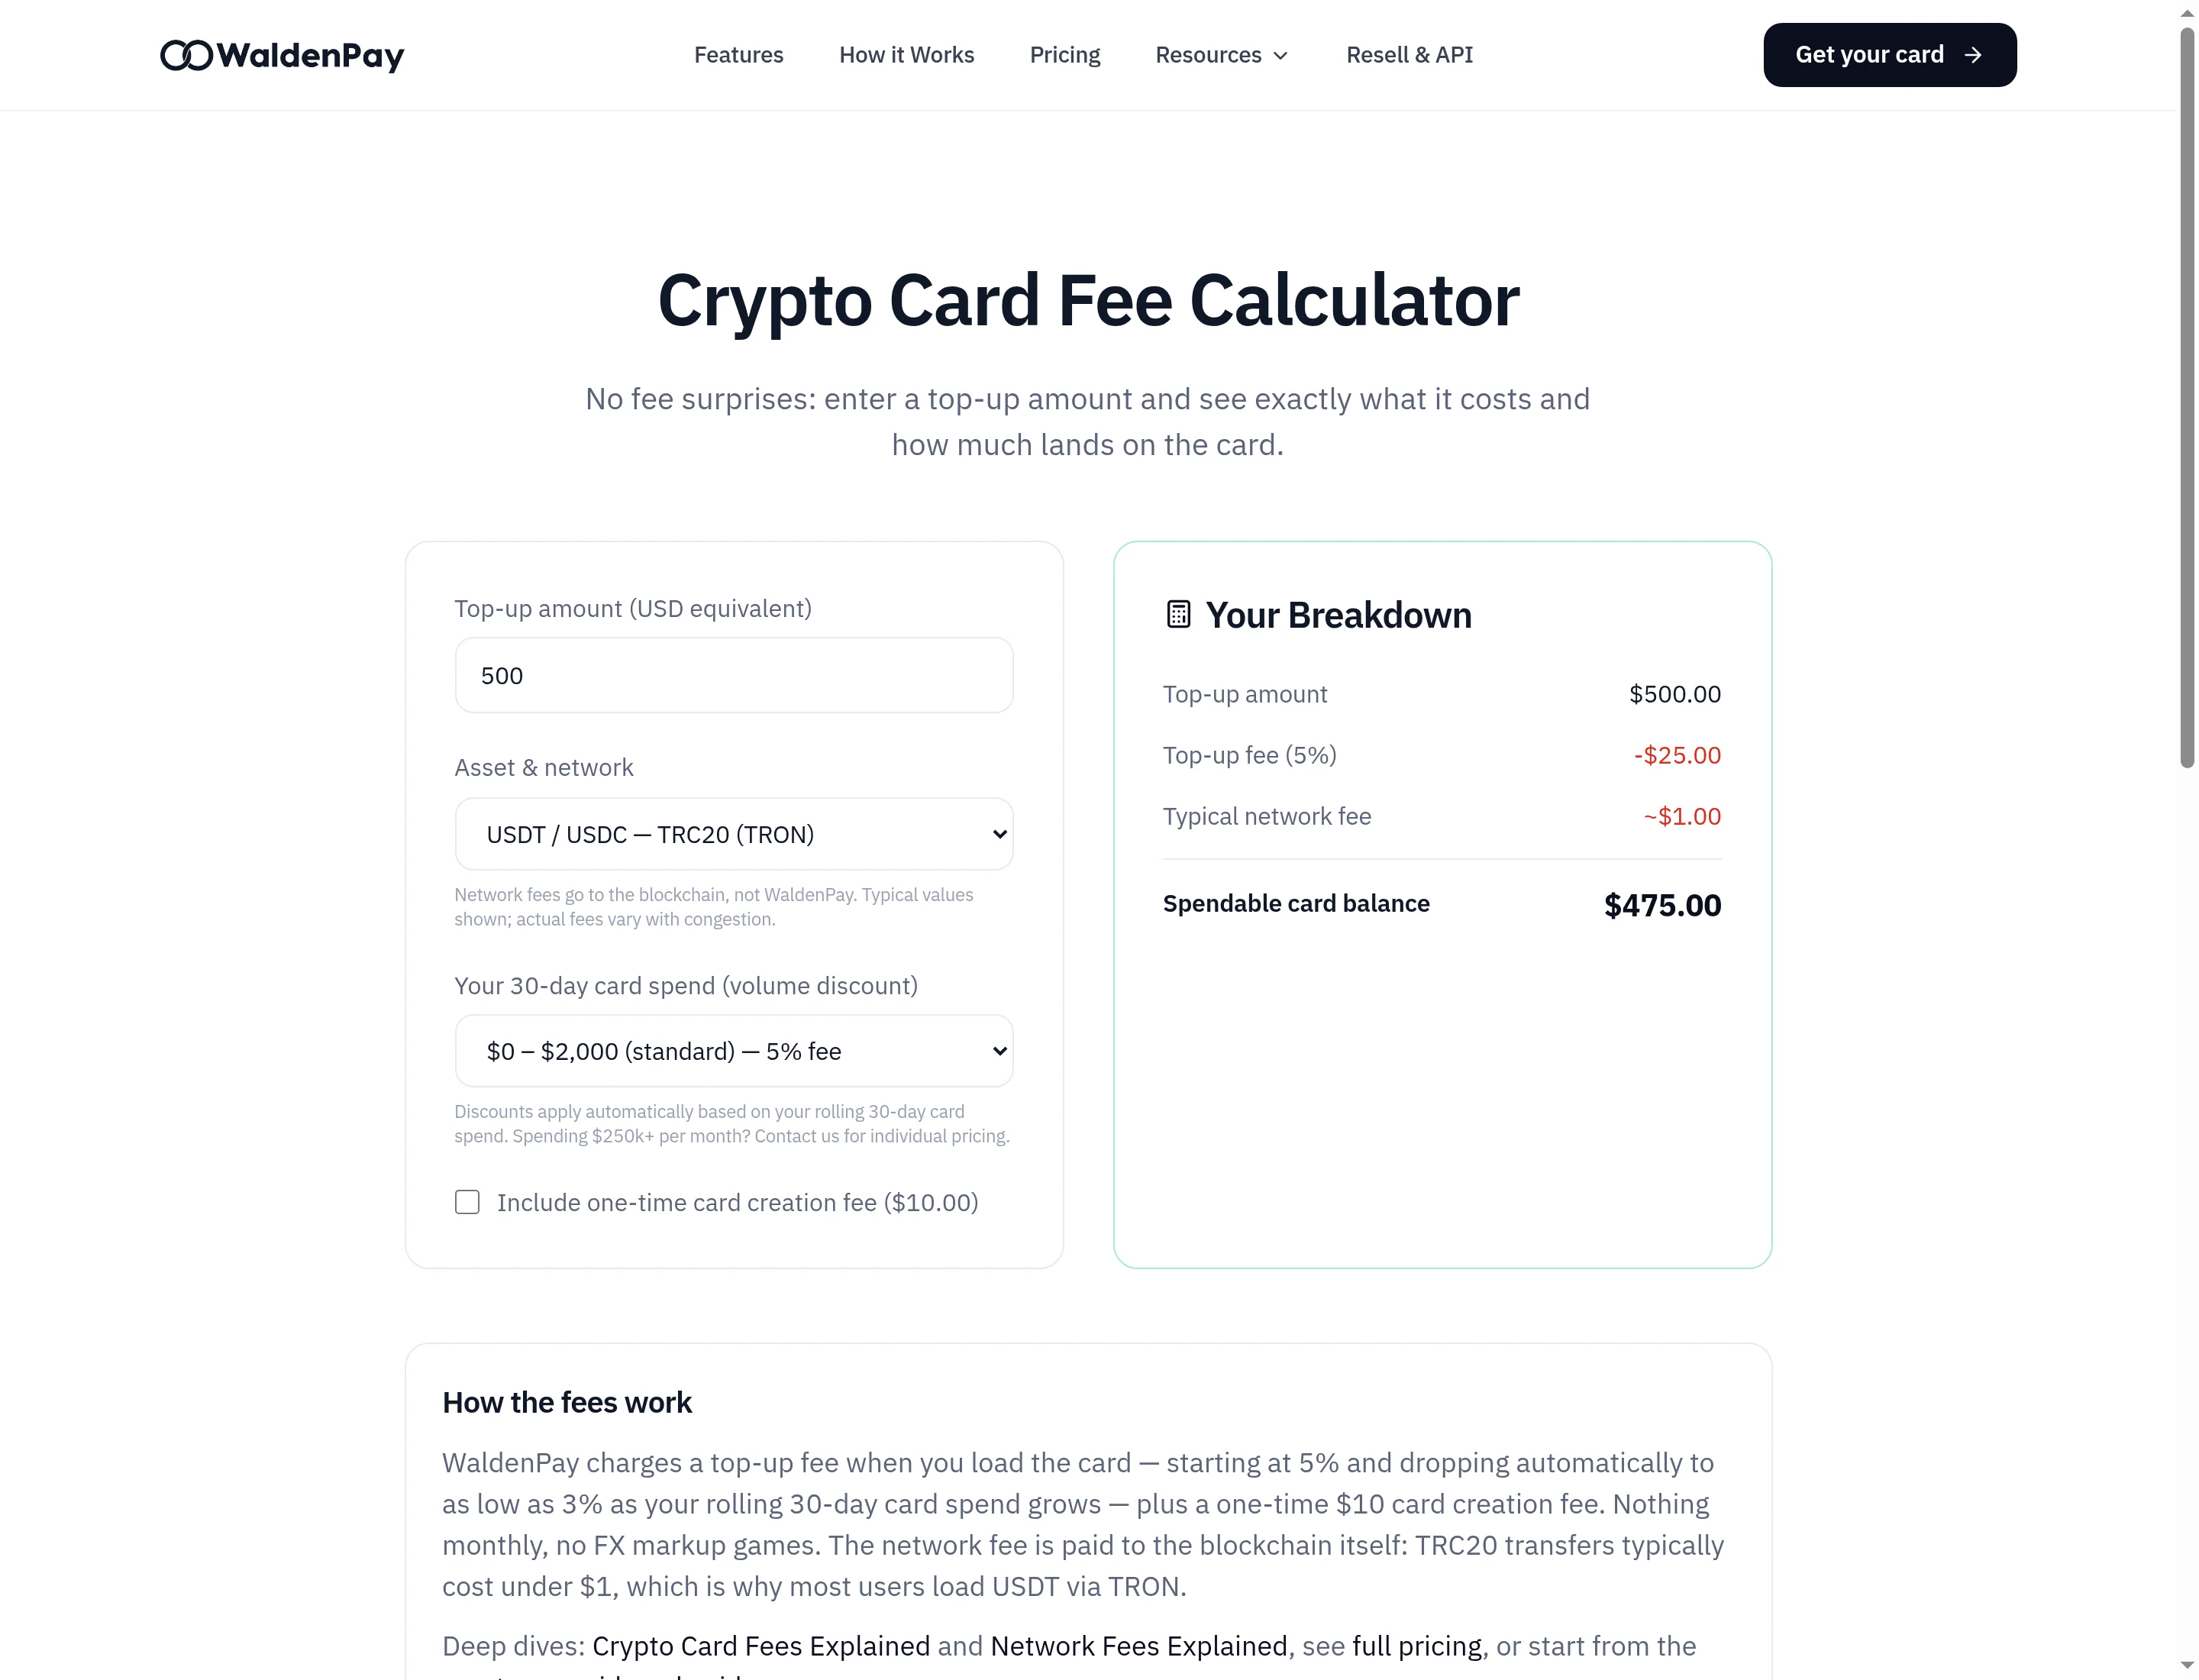
A hypothetical $1,000 top-up fee base produces a $50 charge at WaldenPay's published 5% tier, or $30 at its 3% tier. The difference is $20. This multiplication establishes the fee on the stated base, not the total cash required to deliver $1,000 of spendable balance. The WaldenPay features and fees guide supplies product context.
The funding screen must establish how the fee is presented before the holder confirms. First-card budgeting also includes the separate $10 issue fee. The 2026 feature guide explains funding and usage mechanics; neither a larger deposit nor this hypothetical calculation establishes eligibility for a lower tier.
For stablecoin funding, the USDT card walkthrough adds route-specific context. Any sending-wallet network cost belongs in the funding budget when applicable, supported by the actual transfer quote rather than an invented allowance.
The prepaid crypto card guide explains the prepaid structure behind this example. WaldenPay doesn't provide borrowed spending capacity, and merchant approval isn't guaranteed. Its privacy-focused use remains subject to AML and regulatory requirements.
WaldenPay's Published Costs and Automatic Volume Discounts
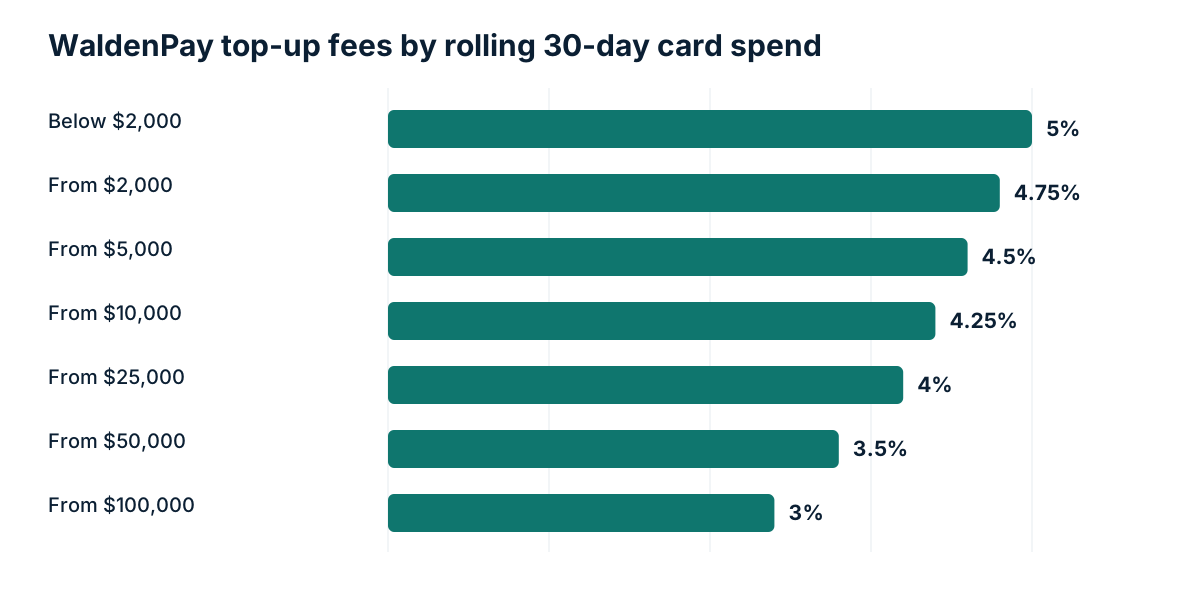
Published-cost example: WaldenPay charges a $10 one-time card issue fee, $0 monthly maintenance, and a top-up fee starting at 5%. The minimum top-up is $25. Registration, balance checks, and support are free.
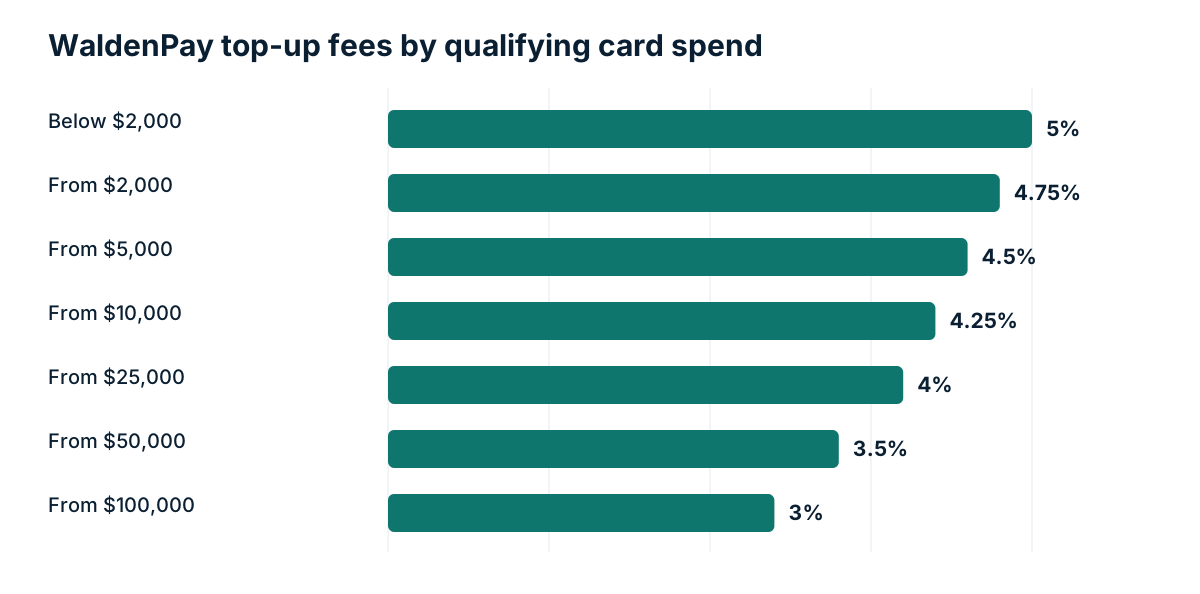
Discounts depend on rolling 30-day card spend, not deposits, account age, or internal transfers. Funding a large balance doesn't itself qualify it for a lower fee. Discounts apply automatically and instantly when the applicable spending level is reached, without an application. The dashboard shows the current fee, rolling spend, and progress toward the next level.
- Below $2,000 in rolling 30-day card spend: 5%.
- From $2,000: 4.75%.
- From $5,000: 4.5%.
- From $10,000: 4.25%.
- From $25,000: 4%.
- From $50,000: 3.5%.
- From $100,000: 3%.
- At $250,000+ per month: individual pricing.
Each published percentage applies until the next threshold. Because the window rolls, a historical spending peak isn't permanent qualification. The displayed tier matters before a recharge; unnecessary purchases merely to reach a discount add spending rather than establish savings.
Collect Payments has a separate 0.2% payer-side conversion fee. The request creator receives the exact requested USD amount in the account wallet. That payment-collection charge isn't the card top-up fee.
Send to Friend provides instant, zero-fee internal transfers. Its $1 minimum, $10,000 per-transfer cap, and $20,000 rolling 24-hour cap aren't card purchase limits. The WaldenPay fee and limit table helps keep these product-specific costs and limits separate.
Calculate Realized Cashback and Paid-Tier Break-Even
An advertised reward rate doesn't show how much value a cardholder ultimately keeps. A useful comparison follows rewards from qualifying purchase through posting, redemption, and any later reversal. For rewards-driven spending, the best crypto card delivers the strongest retained value after costs, rather than simply the largest headline percentage.
Three balances deserve separate tracking: rewards earned under the terms, rewards available to redeem, and rewards retained after refunds. Pending rewards aren't spendable cash. Token rewards shouldn't be valued at an assumed future price.
Build a matched spending worksheet
The calculator should use the same monthly spending basket for every candidate and tier. Excluded purchases remain in total spending when calculating the effective reward rate; otherwise, a narrow rewarded category can make an ordinary spending pattern look unusually profitable.
| Input | Evidence needed | Calculation treatment |
|---|---|---|
| Monthly spending and qualifying share | Settled purchases, category exclusions, and transaction rules | Multiply total spending by the qualifying share |
| Base rate and promotion | Standard rate, promotional duration, and eligibility conditions | Calculate promotional and ordinary periods separately |
| Reward cap | Ceiling, denomination, reset period, and category allocation | Stop accrual at the applicable ceiling |
| Reward currency and redemption | Payout asset, minimum redemption, timing, and charges | Separate estimated token value from realized proceeds |
| Paid access | Subscription, billing period, cancellation, and renewal terms | Subtract incremental charges over the matched period |
| Staking or required holdings | Token quantity, eligibility valuation, and lockup conditions | Record committed capital and liquidity restrictions separately |
| Refunds and reversals | Clawback rules and treatment of redeemed rewards | Remove reversed rewards from retained value |
No provider-specific figures belong in this worksheet without verified regional terms. Missing rates, caps, or subscription prices make a numeric verdict unsupported; they don't justify substituting typical industry values.
Calculate capped rewards before tier break-even
Let S represent monthly settled spending, q the qualifying share, r the reward rate expressed as a decimal, and C a monetary reward cap for that month. Then:
Qualifying spending = S x q.
Gross capped rewards = minimum of (S x q x r) and C.
That formula assumes a single rate and a monetary cap. A spending cap instead limits qualifying purchases before multiplication by r. Category-specific rates require separate calculations, followed by any shared ceiling. Token-denominated caps require the program's documented valuation method.
Promotional ceilings aren't base rewards. The worksheet should calculate each promotional month under its actual conditions, then apply ordinary terms to the remaining comparison period. Annual subscription commitments shouldn't disappear merely because the promotion ends sooner.
Incremental tier value = retained paid-tier rewards - retained base-tier rewards - incremental subscription charges - other verified incremental costs.
For uncapped rewards with identical eligibility, break-even qualifying spending equals incremental fixed cost divided by the incremental reward rate. Break-even total spending equals that result divided by q. If the incremental rate isn't positive, additional spending alone cannot recover the fixed cost.
But a threshold is invalid if exclusions or caps prevent sufficient incremental earnings. Once either tier reaches its ceiling, the calculation becomes piecewise: each spending band needs its own comparison. Payout delays also separate accounting break-even from available cash.
Distinguish paid access from capital at risk
Purchasing a subscription pays for access; staking tokens commits capital whose value may change. A refundable holding isn't automatically a fee, but locked capital isn't freely available. Any opportunity-cost scenario should use the cardholder's stated assumptions, separate from contractual charges.
Token volatility between posting and redemption can reduce usable value. Minimum redemption thresholds, lockups, excluded merchant categories, and later clawbacks can further reduce it. The best crypto card for rewards should remain competitive under ordinary terms, not depend on token appreciation.
Realized cashback rate = retained reward proceeds after redemption costs / total settled purchases in the matched basket. Refunded purchases and their reward reversals need consistent treatment on both sides; subscription charges belong in the separate net-benefit calculation.
Minimum Loads, Spending Caps, and ATM Access Need Separate Checks
A minimum load determines whether funding can begin; it doesn't establish how much can be spent in one purchase. Maximum loads, available balance, purchase caps, ATM allowances, and internal transfer limits answer different questions.
WaldenPay's verified minimum top-up is $25. That prevents a smaller card-loading test, but establishes neither a maximum load nor a purchase ceiling. The minimum top-up guide explains funding thresholds for trial use and small balances.
- Maximum load: Any funding ceiling, separate from purchase permissions.
- Available balance: Funds currently usable, rather than the original deposit.
- Per-transaction cap: The permitted individual purchase size, if specified.
- Aggregate spending limit: A calendar-day or rolling restriction whose reset method needs confirmation.
- ATM allowance: A cash-access rule distinct from purchase limits.
- Transfer limit: A restriction on moving balance, not necessarily spending it.
WaldenPay's Send to Friend permits $1-$10,000 per transfer and up to $20,000 per rolling 24 hours. These are email-based internal transfer limits between WaldenPay users, not card-spending limits.
Small-balance usability depends on whether the remainder covers a suitable purchase and whether another minimum load would commit unwanted funds. Repeated loading isn't automatically more expensive under a percentage-only charge; verified fixed costs would change that assessment. The virtual card spending limits guide distinguishes balance constraints from program restrictions.
And a virtual prepaid card shouldn't be assumed to support ATM withdrawals. Mobile-wallet compatibility doesn't establish cash access, while a physical card doesn't guarantee it either. Format affects practical use where a terminal requires a physical card or supports compatible contactless payments. The virtual versus physical card guide explains those checks without treating format as proof of acceptance.
What Privacy-Focused and No Document Verification Actually Mean
An email-only signup describes registration requirements, not anonymous payment processing. A useful privacy comparison separates account-creation data, documents required for standard use, transaction records, and possible compliance reviews.
WaldenPay signup requires an email only, with no identity documents for standard use. But spending isn't anonymous or untraceable, and use remains subject to AML and regulatory requirements. Those qualifications belong beside the registration claim, rather than in distant fine print.
For privacy-conscious applicants, the best crypto card minimizes unnecessary data collection while explaining its obligations. "No document verification" doesn't promise that additional information can never be requested during a compliance review.
WaldenPay is operated by BlueHouse Software B.V., Rotterdam, Netherlands, through a licensed partner model. It isn't a bank. Identifying the operator distinguishes the service provider from payment-network branding; it doesn't establish a particular protection scheme or guarantee a regulatory outcome.
In the United States, FinCEN's AML guidance provides context on obligations applicable to covered financial businesses. It doesn't establish identical onboarding requirements across card programs.
- Registration: What information is collected, and for what purposes?
- Records: What does the privacy notice explain about sharing, retention, and available privacy requests?
- Verification: Can additional information be required, and how are legitimate requests authenticated?
- Access during review: Which account functions may be restricted while a request remains unresolved?
- Exit: If withdrawals or balance redemption are supported, what verification and destination requirements apply?
These are questions for current terms and verified support channels, not asserted WaldenPay review triggers or thresholds. Eligibility and compliance requirements remain applicable regardless of signup simplicity.
Privacy features don't guarantee approval, unrestricted use, or exemption from merchant rules. Applicants with legal questions should seek qualified professional advice rather than infer protections from a marketing label.
Trace Custody, Wallet Permissions, and Account Security
Control over wallet keys and control over card spending aren't necessarily the same thing. A custodial balance depends on an operator's account system; a wallet-linked card may involve delegated authority, contracts, or intermediaries. Neither model is risk-free.
A useful custody map follows funds through the complete payment lifecycle:
- Deposit: Record the asset's location, the receiving entity or contract, and who holds the private keys. A unique deposit address doesn't establish cardholder ownership of its keys.
- Authorization: Identify who can reserve funds or initiate movement, and whether authority requires a fresh signature or uses an existing allowance.
- Conversion: Establish when crypto becomes card balance or settlement funds, and which entity controls the resulting balance.
- Refund: Confirm the destination and denomination of returned funds, including whether the return depends on continued account access.
WaldenPay provides unique deposit addresses per supported network, and cryptocurrency converts to card balance at loading time. Those facts don't establish self-custody or private-key ownership.
For wallet-linked products, the permission checklist should identify approved assets, spender contracts, allowance amounts, expiry conditions, and documented revocation steps. Disconnecting a wallet interface shouldn't be treated as proof that spending permissions have been revoked. The best crypto card for a self-custody preference still requires scrutiny of delegated authority.
Account checks should cover available authentication methods, recovery procedures, lost-device reporting, and whether card access can be suspended independently of wallet permissions. Mobile-wallet protection also depends on device access controls and recovery settings. The crypto card protection guide provides practical security checks without assuming every program offers identical controls.
Single-use credentials can complicate recurring charges, merchant verification, and refunds that reference an earlier card number. Their suitability depends on documented lifecycle behavior, not just number replacement. The single-use virtual cards guide explains those tradeoffs; WaldenPay shouldn't be assumed to issue disposable cards.
Check Merchant Holds, Refunds, Disputes, and Exit Options
A successful purchase is only one part of card usability. Funds can remain reserved before settlement, refunds can follow a different path from purchases, and account closure can complicate access to an outstanding credit. The relevant evidence is the card agreement and support procedure, not the network logo alone.
Separate reserved funds from completed charges
An authorization hold reserves spending capacity while a payment is pending. Capture completes the merchant's charge against that authorization. An authorization reversal cancels or reduces a reservation; a merchant refund returns funds after a completed charge. These events shouldn't be treated as interchangeable entries.
In a hypothetical purchase, a $100 hold followed by an $80 final charge leaves a $20 difference to reconcile. That difference isn't another purchase or automatically a posted refund. Available balance may not reflect its release immediately; timing depends on the applicable processing and program rules. No universal release deadline should be assumed.
And a pending hold can reduce usable balance even when the final purchase is smaller.
| Event | Documentation to check | Record to retain |
|---|---|---|
| Authorization hold | How reservations affect balance and how stale holds are investigated | Pending amount, date, and merchant reference |
| Capture or reversal | How final amounts replace or release reservations | Final receipt and matching transaction entry |
| Merchant refund | Return destination, denomination, and tracking process | Refund confirmation and reference |
| Disputed payment | Reporting channel, evidence, deadlines, and review procedure | Transaction details and supporting correspondence |
| Account closure | Residual balance and outstanding-credit procedures | Statements and closure confirmation |
Check the merchant's payment lifecycle
Hotel and rental bookings need checks beyond the advertised purchase price: whether prepaid credentials are permitted, whether a deposit is required, whether a physical card must be presented, and how additional authorizations are handled. These are generic due-diligence questions, not claims that a particular card or merchant supports those transactions.
For subscriptions, cardholders should distinguish canceling the service from disabling a payment credential. Freezing or replacing a card shouldn't be assumed to cancel the underlying agreement. Documentation should explain recurring-payment treatment and any process for challenging charges after cancellation.
Online purchases add partial shipments, canceled items, and split captures. A cardholder should match each settled amount to its order record before treating multiple entries as duplicate charges.
Follow refunds to their actual destination
The refund policy should state whether money returns to card balance, account balance, or cryptocurrency. A crypto-funded purchase doesn't by itself establish a crypto refund. If a return involves crypto, the denomination and valuation method require explicit documentation rather than inference.
- Can a refund reach an expired, replaced, frozen, or closed card?
- Which party traces a missing credit, and what reference is required?
- Are reward reversals processed separately from the purchase refund?
- What happens if the account is under review when funds return?
Document disputes and departure before funding
A merchant refund request differs from a formal chargeback dispute. Dispute routes and protections depend on applicable terms and law; a network-branded card doesn't guarantee reimbursement. Unauthorized transactions should be reported promptly through the program's designated channel, without assuming a merchant conversation replaces formal notice.
Useful evidence includes receipts, order descriptions, delivery records, cancellation confirmations, refund promises, and dated correspondence. The checklist should establish submission deadlines, status tracking, whether any temporary credit is available, and how an unfavorable decision can be challenged. Availability shouldn't be presumed.
For ongoing use, the best crypto card also needs a documented exit route. Before funding, applicants should establish how remaining balance can be redeemed, whether minimums or documented charges apply, how pending disputes survive closure, and how statements remain accessible. If those answers aren't published, written clarification should precede a larger commitment.
Separate Prepaid Spending From Borrowing and Liquidation Risk
A prefunded card exposes money already committed to spending; a borrowing product adds an obligation to repay. That distinction matters more than whether both products carry the same card-network logo.
Prefunded balances: price risk before loading, access risk afterward
With a prepaid model, the holder funds a balance before purchases occur. If the funding asset falls in value before conversion, more crypto may be needed to establish the intended spending balance. Stablecoins reduce exposure to some price movements, but a stable price target isn't a guarantee. A depeg can reduce the value available for loading, while network congestion or a suspended funding route can delay access.
WaldenPay converts cryptocurrency into card balance at loading time. Once conversion is complete, subsequent movements in the original funding asset don't change that loaded balance. The holder also no longer participates in a price increase through those converted funds. This is prepaid spending, not a loan secured by the original cryptocurrency.
But conversion doesn't remove operational risk. A custodial service interruption, account review, or unavailable card service can restrict access to funds. The relevant questions concern who controls each balance, what contractual protections apply, and how access can be restored. Keeping essential spending dependent on one account concentrates that exposure.
Conventional credit: repayment obligations without crypto collateral
A conventional credit card that pays rewards in crypto can leave purchases entirely separate from crypto funding. The borrower owes the card bill under the credit agreement; the reward asset is a separate exposure. Interest, payment deadlines, late-payment consequences, and any applicable charges need assessment even when the reward headline looks attractive.
A decline in reward-token value doesn't ordinarily create a collateral call on an unsecured card. It can still reduce the economic value of rewards, while unpaid debt remains due. Applicants should establish whether the product is genuinely conventional credit rather than infer its structure from the word "credit."
Crypto-backed borrowing: the collateral can move against the debt
Loan-to-value, or LTV, compares outstanding debt with the current value of eligible collateral. The following example is explicitly hypothetical, not a provider's offer or liquidation policy:
- A $500 loan against $1,000 of collateral has 50% LTV: $500 divided by $1,000.
- If collateral falls to $800 while debt remains $500, LTV rises to 62.5%.
- Neither percentage establishes when a provider would issue a warning, restrict borrowing, or liquidate collateral.
Actual maintenance thresholds, borrowing rates, eligible collateral, valuation methods, and liquidation charges must come from the relevant agreement. Accruing interest can increase debt even without additional purchases. A lender may also change the eligible value assigned to an asset under its terms, so the displayed market price alone may not explain borrowing capacity.
Before considering this model, applicants should identify the warning and liquidation thresholds, notification method, any cure period, and whether liquidation is automatic. Adding collateral or repaying debt may reduce LTV, but transfers can be delayed and intervention may not arrive in time. Liquidation can sell assets at an unfavorable moment and may have tax consequences.
The best crypto card for spending an existing balance isn't necessarily suitable for retaining leveraged crypto exposure. Those are different financial jobs, with different failure modes.
Keep Records for Crypto Disposals, Rewards, and Borrowing
Spending USDT can have US tax and reporting consequences even when its market price stays close to its target. The IRS treatment of digital assets generally treats them as property for federal income tax purposes. A stable price target doesn't eliminate the need to establish acquisition cost, proceeds, and any gain or loss.
Timing depends on the product mechanics. Where crypto is converted when a prepaid card is loaded, that loading transaction is the potential disposal to document; later purchases spend the resulting card balance. A product that sells crypto as purchases occur creates a different transaction trail. The guide to USDT card tax considerations expands on that distinction without treating every card purchase as mechanically identical.
- Acquisition records: purchase dates, quantities, dollar values, cost basis, and associated fees.
- Funding evidence: transaction hashes, networks, deposit addresses, conversion confirmations, and timestamps.
- Card activity: statements, purchase receipts, refunds, reversals, and recorded charges.
- Rewards: award dates, asset quantities, recorded values, and program terms.
- Borrowing: loan agreements, draws, repayments, interest records, collateral movements, and liquidation statements.
Rewards can receive different treatment depending on how they're earned. Borrowing also needs separate analysis from selling crypto, while a later collateral liquidation may introduce disposal consequences. Refund records should preserve both the original transaction and its reversal rather than simply erase the purchase. A qualified US tax professional can assess the actual arrangement and applicable federal and state obligations; these records support that assessment rather than establish a universal tax rule.
Follow a Step-by-Step Check Before Applying or Funding
A useful shortlist ends with evidence, not an application button. The best crypto card should survive the same checks whether its strongest selling point is privacy, rewards, mobile-wallet access, or a broad funding list. Each step below should produce a saved answer or an unresolved question that blocks funding.
-
Residence eligibility comes first. The applicant records the supported country and, where relevant, state; the contracting entity; whether new applications are open; and the date checked. Virtual issuance, physical delivery, and overseas purchasing are separate questions. An acceptance claim about international merchants doesn't establish eligibility for a US resident.
-
The spending job becomes a written requirement. The shortlist should specify whether the card is intended for subscriptions, everyday mobile-wallet purchases, business expenses, travel reservations, or cash access. Essential capabilities become pass-or-fail gates. Optional rewards shouldn't compensate for a missing function needed for routine spending.
-
The funding model matches the intended exposure. Applicants distinguish prepaid loading, purchase-time crypto sales, conventional credit, and collateralized borrowing. They identify when crypto leaves their control and when its value becomes committed to spending. Anyone unwilling to monitor collateral should exclude products requiring that ongoing management.
-
The exact asset-network pair is verified. The receiving interface must support both the intended token and its network. The applicant saves the funding instructions, checks any required memo or tag, and confirms that the sending platform supports the same route. A token symbol alone isn't adequate transfer evidence.
-
Wallet requirements are confirmed before connection. The review establishes whether funding uses a normal transfer, a custodial account, or a wallet authorization. For connected wallets, the applicant examines permitted assets, spending permissions, and revocation instructions. Mobile-wallet provisioning is checked separately; funding-wallet compatibility doesn't establish tap-to-pay compatibility.
-
The fee schedule is captured in its current form. Saved evidence should cover issuance, loading, subscriptions where applicable, and optional services relevant to the intended use. Conditional discounts need their qualification basis recorded. For WaldenPay, automatic top-up discounts depend on rolling 30-day card spend, not the amount deposited into the account.
-
Minimums and limits are assigned to the right operation. Funding minimums, purchase caps, account-transfer caps, and any supported cash-withdrawal limits need separate entries. Unpublished limits remain unresolved rather than becoming assumed allowances. WaldenPay's $25 minimum top-up is a funding requirement; Send to Friend limits describe a different service.
-
Merchant-policy fit is checked before commitment. The applicant establishes whether intended merchants permit prepaid or virtual cards and whether reservations require a physical card or additional security. Recurring billing and authorization holds deserve explicit attention. Merchant acceptance and successful approval remain conditional, even after a card has worked elsewhere.
-
Custody and recovery receive a practical review. The evidence should identify the entity responsible for each balance, available account-security controls, and recovery procedures after loss of email, phone, or wallet access. Support contact details should be saved outside the account. Recovery requirements matter before funds become inaccessible, not only afterward.
-
Refund and exit terms close the review. The applicant records where refunds arrive, how disputed purchases are reported, and how remaining funds can be redeemed if the card is closed. Fee schedules, eligibility pages, support clarifications, and relevant agreement versions stay together with their dates. Marketing screenshots alone aren't sufficient evidence.
Only after these checks does a suitably small permitted funding and purchase test become useful. For WaldenPay, an initial load must meet the published $25 minimum, with the $10 one-time card issue fee and applicable top-up fee accounted for. A low-stakes purchase can test authorization and statement visibility, but it doesn't prove future acceptance or replace written terms. Unexpected results should pause further funding until the cause is understood.
Avoid the Mistakes That Make a Suitable Card Expensive or Unusable
Many failures start with a correct fact applied to the wrong operation. A network can be supported while a particular deposit route isn't; an internal transfer can be permitted while a card purchase is declined. The diagnostic task is to identify which rule actually governs the failed action.
| Mistake | Likely consequence or signal | Prevention and legitimate next step |
|---|---|---|
| Confusing merchant reach with residence eligibility | The application stops despite a broad worldwide acceptance claim. | Applicants verify supported residence and current issuance status before depositing. An eligibility restriction calls for an eligible alternative, not a different claimed address. |
| Sending the correct token on the wrong network | A transfer appears completed on-chain but doesn't credit the account. | The sender compares the actual network, receiving address, and deposit instructions. Support receives the transaction hash and route details; recovery isn't assumed. |
| Treating email-only signup as anonymity | An account review or request for information contradicts the holder's expectations. | Privacy claims are read alongside compliance terms. WaldenPay requires only an email for signup and no identity documents for standard use, but remains subject to AML and regulatory requirements. |
| Mistaking load volume for qualifying card spend | A larger deposit doesn't produce the expected top-up discount. | The holder checks the qualification basis. WaldenPay uses rolling 30-day card spend, with the dashboard showing the current fee and progress toward the next tier. |
| Choosing a paid rewards tier before checking exclusions | A subscription cost is incurred while routine purchases earn less than expected. | The applicant checks eligible purchases, caps, reward currency, and mandatory holding conditions before paying. Only qualifying spending belongs in the break-even calculation. |
| Treating internal transfer caps as purchase limits | A planned purchase depends on a limit that governs another feature. | Each limit is labeled by operation. WaldenPay's Send to Friend allows $1-$10,000 per transfer and $20,000 per rolling 24 hours; those figures don't establish card-purchase limits. |
| Assuming a prepaid card overrides merchant rules | A merchant rejects the card type or requires a different payment instrument. | The holder reads the decline message and merchant terms. A merchant-approved alternative or support clarification is appropriate; repeated attempts don't change the merchant's policy. |
A missing deposit and a declined purchase need different evidence. For the deposit, useful records include the transaction hash, network, amount sent, destination, and time. For the purchase, the merchant, amount, timestamp, displayed decline reason, and any pending authorization are more relevant. Support should receive only the information needed through an authenticated channel, never a wallet recovery phrase.
And an unexpected charge needs its fee basis checked before another load is attempted. The account's recorded tier, qualifying spending window, and transaction receipt help distinguish a misunderstood rule from a possible error.
The best crypto card won't eliminate every interruption. A clear explanation, documented escalation route, and willingness to stop funding when facts conflict are more useful than repeated retries or larger deposits intended to force an unresolved transaction through.
What Crypto Adoption and Payment Trends Mean for Card Choice
Adoption rankings, ownership estimates, stablecoin transaction activity, and card eligibility answer different questions. A country can show substantial crypto use without a particular card accepting residents there. The research on crypto adoption by country provides context for regional activity, but application decisions still require current provider terms. Stablecoin transfer statistics also need their methodology checked: trading, treasury movements, and repeated transfers can contribute to activity without representing retail purchases. Market size isn't a substitute for a verified funding route or an eligible application.
Ownership figures are similarly sensitive to definitions, survey coverage, and whether estimates count people, accounts, or addresses. The discussion of global crypto ownership estimates helps frame those distinctions rather than prove that a card is widely usable. For an individual applicant, multi-network funding matters when it matches assets already held and routes actually available from the sending wallet. Mobile-wallet support matters when intended merchants accept contactless payments and the card can be provisioned successfully. Neither feature guarantees approval.
Payment links add a receiving function rather than change the nature of card spending. The analysis of cryptocurrency payment trends places these tools in context without making forecasts a selection criterion. WaldenPay's Collect Payments lets a creator request a fixed USD amount through a link or QR code; the payer doesn't need an account, and the creator receives the requested amount in the wallet. Subsequent prepaid card funding remains a separate operation with its own terms.
Bottom Line: Which Crypto Card Should Make the Final Shortlist?
The best crypto card earns its place by solving a specific payment problem at an acceptable cost, after residency eligibility is confirmed.
Existing-crypto spending favors a funded debit or prepaid model that supports the holder's exact asset and network. Rewards-focused applicants need verified net rewards after fees, caps, and tier requirements, plus credit terms suited to their repayment capacity. Custody-focused holders should establish who controls the wallet's private keys, what spending permissions remain active, and how those permissions can be revoked. A wallet connection alone doesn't establish control throughout the payment process.
And travel or cash requirements need explicit checks for overseas use, hotel deposits, physical-card requirements, and ATM access. Merchant-network reach doesn't establish those capabilities or guarantee acceptance.
WaldenPay is a conditional shortlist option for eligible users seeking multi-asset virtual prepaid spending: it supports funding with 135+ cryptocurrencies across 35+ networks, with conversion to card balance at loading. Its $10 issue fee, $25 minimum top-up, and top-up fees starting at 5%, falling automatically to 3% with qualifying spending volume, must fit the budget. There's no monthly maintenance fee. Published limits still apply, and privacy-focused use remains subject to AML and regulatory requirements.
An ordinary payment card may fit better when crypto funding adds cost without solving a problem. Direct crypto payment may suit a willing merchant when both parties accept the network and refund arrangements. The Benefits of Crypto Cards article explains where card access adds practical utility beyond holding or transferring crypto.
Put Eligibility Before Adoption Trends
Crypto adoption figures don't establish individual card eligibility or merchant acceptance. A WaldenPay shortlist decision should rest on eligibility checks and published costs: a $10 one-time card issue fee, top-up fees from 5% down to 3% with automatic volume discounts, and no monthly maintenance fee.
Frequently Asked Questions
What is the best crypto card for someone who mainly holds USDT?
The best crypto card for a USDT holder depends on country eligibility, the supported USDT network, and the cost of funding the intended spending amount. A USDT payment card should support the exact network used by the holder's wallet, not just list USDT as an asset. Rewards matter less if funding costs outweigh the cashback actually earned.
How do crypto cards work if a store doesn't accept cryptocurrency?
Crypto cards let merchants accept a card payment rather than receive cryptocurrency directly. With WaldenPay, crypto converts to card balance at loading time, and purchases use a virtual prepaid card on Visa/Mastercard rails. The merchant doesn't need a crypto wallet, but its card acceptance rules still apply.
Can U.S. residents apply for every crypto card accepted in the United States?
No, merchant acceptance in the United States doesn't establish eligibility for U.S. residents. Applicants should check the provider's current country eligibility and applicable terms before depositing funds. A worldwide merchant acceptance figure isn't a list of countries where cards can be issued.
How can a holder check whether an Arbitrum crypto card or Polygon USDT card supports a deposit?
The funding screen must show the intended asset and network together before a deposit is sent. Support for USDT or USDC alone doesn't confirm support for every network carrying that token. WaldenPay provides unique deposit addresses per supported network, so the sender must match the selected route rather than assume one address works across networks.
Does an instant USDC virtual card become usable immediately after signup?
Instant issuance doesn't necessarily mean a card is ready immediately after an email signup. WaldenPay issues the card instantly after funding, with crypto converting to card balance at loading time. Funding completion and any required compliance checks remain separate from card issuance, and availability isn't guaranteed.
What is the prepaid card minimum load amount for WaldenPay?
WaldenPay's minimum card top-up is $25. Its one-time card issue fee is $10, and top-ups carry a fee starting at 5%, with automatic volume discounts down to 3%. The minimum load isn't an all-in cost quote, so the funding summary should be checked before confirmation.
Does a large deposit qualify for a crypto card volume discount?
At WaldenPay, discounts depend on rolling 30-day card spend, not the size of a deposit. The top-up fee starts at 5%, falls to 4.75% from $2,000 in qualifying spend, and reaches 3% from $100,000, with additional tiers between those thresholds. Discounts apply automatically, and the dashboard shows the current fee and progress toward the next tier.
Does no document verification mean a crypto card is anonymous?
No, the absence of identity-document collection for standard use doesn't make card spending anonymous or untraceable. WaldenPay requires an email for signup and no identity documents for standard use, but use remains subject to AML and regulatory requirements. Privacy-focused describes limited data collection, not an exemption from compliance checks.
Can a crypto prepaid card be used for subscriptions, hotels, and car rentals?
Acceptance depends on the merchant's current prepaid-card policy and any authorization-hold requirements. As of July 2026, merchant-specific terms should be checked before a subscription or reservation depends on a crypto prepaid card. Adding a card to Apple Pay or Google Pay doesn't change its prepaid status or guarantee approval.
Does spending USDT on a card create a U.S. tax obligation?
Converting or disposing of USDT to fund spending can have U.S. tax consequences, even when its value stays close to $1. Records should include acquisition cost, the amount disposed of, transaction dates, and associated fees. A qualified tax professional can assess the holder's reporting obligations; a stablecoin label alone doesn't determine the tax treatment.
Will a refunded crypto card purchase return the original cryptocurrency?
A merchant refund shouldn't be assumed to restore the original cryptocurrency or token quantity. WaldenPay converts crypto to card balance when loaded, so the original funding transaction is separate from a later purchase refund. Cardholders should check the applicable refund destination, timing, and withdrawal terms before relying on access to returned funds.
Does an XRP debit card or altcoin debit card spend tokens directly from a personal wallet?
The card's label doesn't establish whether it spends directly from a personal wallet or requires assets to be transferred and converted first. WaldenPay supports funding with 135+ cryptocurrencies across 35+ networks, but funded crypto converts to card balance at loading time. An altcoin holder should verify the exact funding route and custody terms rather than assume the card preserves on-chain ownership until each purchase.